Alex's Wake-Up Call: How a Simple Side Hustle Turned Into a Tax Bill
This article first appeared as an X Article in February 2026.
Meet Alex (not his real name), a 35-year-old accountant from Nakuru. By day, he crunches numbers at a mid-sized firm, taking home about KSh 71,000 after deductions from his KSh 100,000 gross salary. But like many Kenyans navigating a tough economy, Alex has a side hustle: he sells second-hand electronics online through social media and from a small shop on weekends. Last year, his side gig brought in KSh 2.5 million in gross sales. Nothing extravagant, just enough to cover school fees and save a bit for emergencies.
Alex thought he was flying under the radar, declaring only his salary in his annual tax returns. Then, in early 2026, he got a nudge from the Kenya Revenue Authority (KRA) through his iTax portal: his side hustle qualified for Turnover Tax (TOT). Suddenly he owed 1.5% on those sales, about KSh 37,500 for the year, plus possible penalties for late registration. "I wasn't hiding anything," Alex says, "but I didn't know my online sales counted as a 'business' under the law."
Stories like Alex's are becoming common as KRA tightens the net on informal incomes. So what exactly is this "side hustle tax," and should you be worried?
Understanding the Side Hustle Tax: Turnover Tax Explained
In Kenya, side hustles (freelancing, online sales, small trading, gig work) are increasingly in the tax spotlight. The main tool is Turnover Tax (TOT), a simplified presumptive tax for small businesses. TOT applies to any resident person or entity whose gross turnover (total sales before expenses) is more than KSh 1 million but does not exceed, and is not expected to exceed, KSh 25 million in a year of income. It is charged under section 12C of the Income Tax Act (Cap. 470), at 1.5% of gross sales. The Finance Act, 2023 raised the rate to 3% from July 2023; KRA’s subsequent guidance records the reduction to 1.5% in March 2024.1
For side hustles, this means that if your extra income counts as business turnover, you pay TOT instead of the standard 30% corporate income tax or folding it fully into your personal income tax (though you can opt out if you prefer detailed accounting).
TOT isn't new; it dates back to 2007. But enforcement has stepped up with digital tools like the Electronic Tax Invoice Management System (eTIMS), which requires businesses to issue electronic invoices. Recent updates push automation, making evasion harder. For digital side hustles there is also the Significant Economic Presence (SEP) tax for non-residents, but locals fall under TOT or personal income tax.
When Does It Come Into Force?
TOT is already in force. Its current 1.5% rate dates from March 2024, not mid-2023. KRA began validating 2025 income tax returns against TIMS/eTIMS, withholding-tax and Customs records from 1 January 2026, subject to the applicable statutory exceptions. For the 2025 year of income, KRA subsequently allowed valid business expenses without eTIMS/TIMS invoices to be uploaded for validation after submission. This is not a blanket rejection of every non-eTIMS expense. TOT itself is charged on gross sales without expense deductions, so expense disallowance should not be presented as increasing the TOT base. References to Finance Bill 2025 proposals are historical: the Finance Act, 2025 had already been enacted before this article first appeared in February 2026.
If your eligible business turnover is more than KSh 1 million and does not exceed KSh 25 million, check your TOT registration and filing obligations. TOT returns and payments are due by the 20th of the following month. TOT is a final tax on that income: an annual income tax return is not required in respect of the income already subject to TOT. Other income, such as Alex’s employment income, can still create annual return obligations, normally due by 30 June for an individual’s preceding calendar year.
Street Sentiments: What Kenyans Are Really Saying About the Side Hustle Tax
Turnover Tax, often called the "side hustle tax," has Kenyans talking everywhere from chama meetings and barbershops to WhatsApp groups and X threads. On the streets, the conversation is raw, passionate and split down the middle. Here's the pulse from everyday hustlers, small business owners and online voices in 2025–2026.
The Cheers: Why Some Say It's Long Overdue
Many people, especially in the formal sector (where every shilling is taxed at source before it can even consider a life of non-compliance), see TOT as a fair shake. "Tulipe ushuru tujitegemee" (let's pay taxes to be self-reliant) echoes in pro-compliance circles. Other supporters say the flat 1.5% on gross turnover is simple: no complicated profit calculations or expensive accountants. It's far lighter than the 30% corporate rate, and it helps level the field so salaried folks aren't carrying the whole load while informal earners skate free.
In informal conversations, whether among colleagues or at family gatherings, there is often (understandably) some scepticism about how well taxes are used. Still, many accept that, if managed properly, Turnover Tax revenue can help pay for essential public services such as roads, hospitals and schools. Some approve of KRA's push for eTIMS and automation, saying it cuts corruption and makes compliance easier in the long run. A formalised hustle can also get loans, tenders and credibility. Some online voices celebrate it as a step toward a modern, transparent economy where everyone chips in.
The Gripes: Why Others Call It a Hustle Killer
On the flip side, the streets are loud with frustration. Critics call TOT punishing, mainly because it's charged on gross sales, not profit. Low-margin hustles (think mitumba sellers, mama mbogas or online resellers) get hammered even when they're barely breaking even or making a loss. "It's taxing turnover, not success," one common complaint goes. Many say it forces small players to dip into capital just to pay, stifling growth in an economy already squeezed by high living costs, VAT hikes and fuel levies. Youth unemployment is sky-high, and over-taxing the "digital hustle" or weekend gigs feels like kicking people who are just trying to survive.
There's anger that big corporates have loopholes while jua kali operators face aggressive audits and eTIMS rules that could "kill informal suppliers" and make business impossible without formal invoices. Recent changes, like the stricter 2026 expense validations, have small business owners warning of a "winter" for the micro-economy. Online and in protests, people link it to wider over-taxation that pushes hustlers underground or abroad.
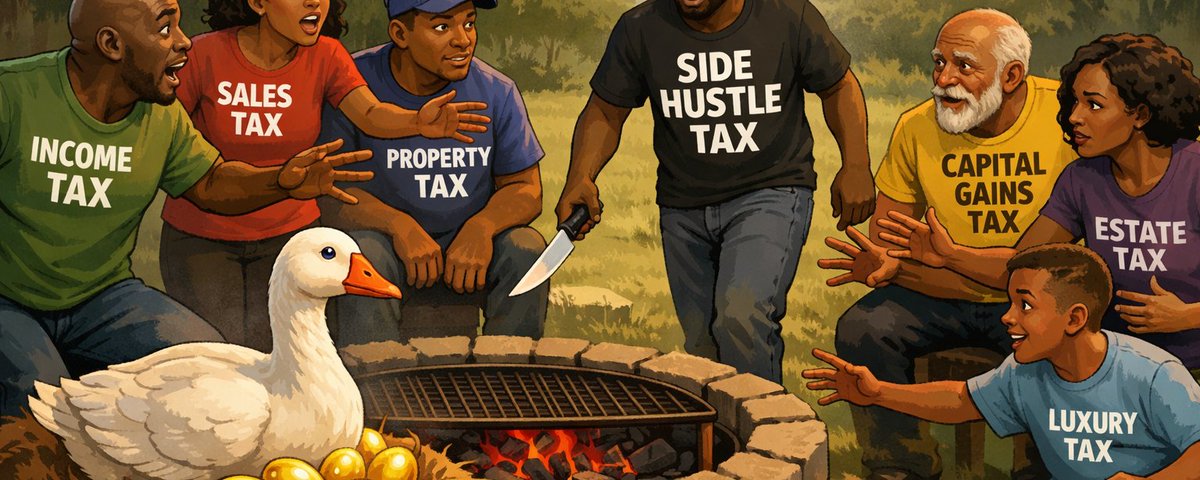
The debate rages on X, in opinion pieces and at every street corner. Is TOT nurturing small businesses or squeezing them dry? Is it a fair contribution or an extra burden on the little guy? For hustlers like Alex, these sentiments hit home. Compliance might bring peace, but fear of penalties and the grind of tracking every sale keep many on edge. The golden eggs are still enticing; the question is whether the so-called "side hustle tax" is just sharing in the yield or risking the goose itself. What's your take from the streets? Drop it in the comments.
Conclusion
In the end, Kenya's side hustle tax, through Turnover Tax and faster eTIMS enforcement, is a clear sign that the days of informal earnings staying completely off the radar are ending. For hustlers like Alex, the message is simple but sobering: a weekend gig to make ends meet can quickly become another line on your tax return once gross turnover passes KSh 1 million a year. The policy is part of a wider national push toward a more digital, transparent and inclusive tax system.
Supporters see it as essential for closing revenue gaps, funding public services and levelling the field between salaried workers and informal entrepreneurs. Critics warn that a 1.5% levy on turnover, whatever the profit, can feel punitive to low-margin businesses, discourage risk-taking in an already tough economy, and put extra pressure on young people trying to build something from nothing. Whether you see it as necessary modernisation or overreach on the Kenyan hustle, one thing is certain: ignorance of the rules is no longer a viable strategy. KRA's automated systems, monthly filing requirements and growing use of digital trails mean compliance is becoming unavoidable for anyone earning meaningfully from a side venture.
The practical advice is straightforward:
- Track your gross sales religiously: every M-Pesa till transaction and every bank deposit tied to the hustle.
- Check your Turnover Tax registration on iTax when your eligible business turnover is more than KSh 1 million and does not exceed KSh 25 million. Rental income, management, professional and training fees, and income subject to final withholding tax are excluded; an eligible person may elect in writing to be taxed under the other Income Tax Act provisions.
- Use eTIMS for invoicing if your business supplies goods or services.
- Consider registering voluntarily even below the threshold if it gives you credibility for loans, tenders or partnerships.
- Keep good records (receipts, bank statements, expense logs) so you can defend your numbers if you're audited.
For Alex, the wake-up call came just in time. He registered, started issuing eTIMS invoices, and is on course to pay his first TOT instalment. It won't be painless, but for now it has bought him peace of mind. Thousands of other Kenyans are in the same position: deciding whether to formalise their hustle or risk falling foul of an increasingly watchful KRA. If you run a side gig, check your numbers today. Better to know where you stand than to be surprised tomorrow.
Search terms for updates: "Kenya Turnover Tax 2026", "KRA eTIMS side hustle", "TOT registration guide Kenya".
This article is general information, not tax advice. Speak to a professional about your specific circumstances.
Originally published on X: Alex's Wake-Up Call. By Benjamin Manani, Ben Manani & Co. Advocates.
-
Kenya Revenue Authority, Turnover Tax guidance: kra.go.ke. ↩
-
ClearTax Kenya, commentary on eTIMS expense validation: cleartax.co.ke. ↩
-
Cliffe Dekker Hofmeyr, Finance Bill 2025 commentary: cliffedekkerhofmeyr.com. ↩